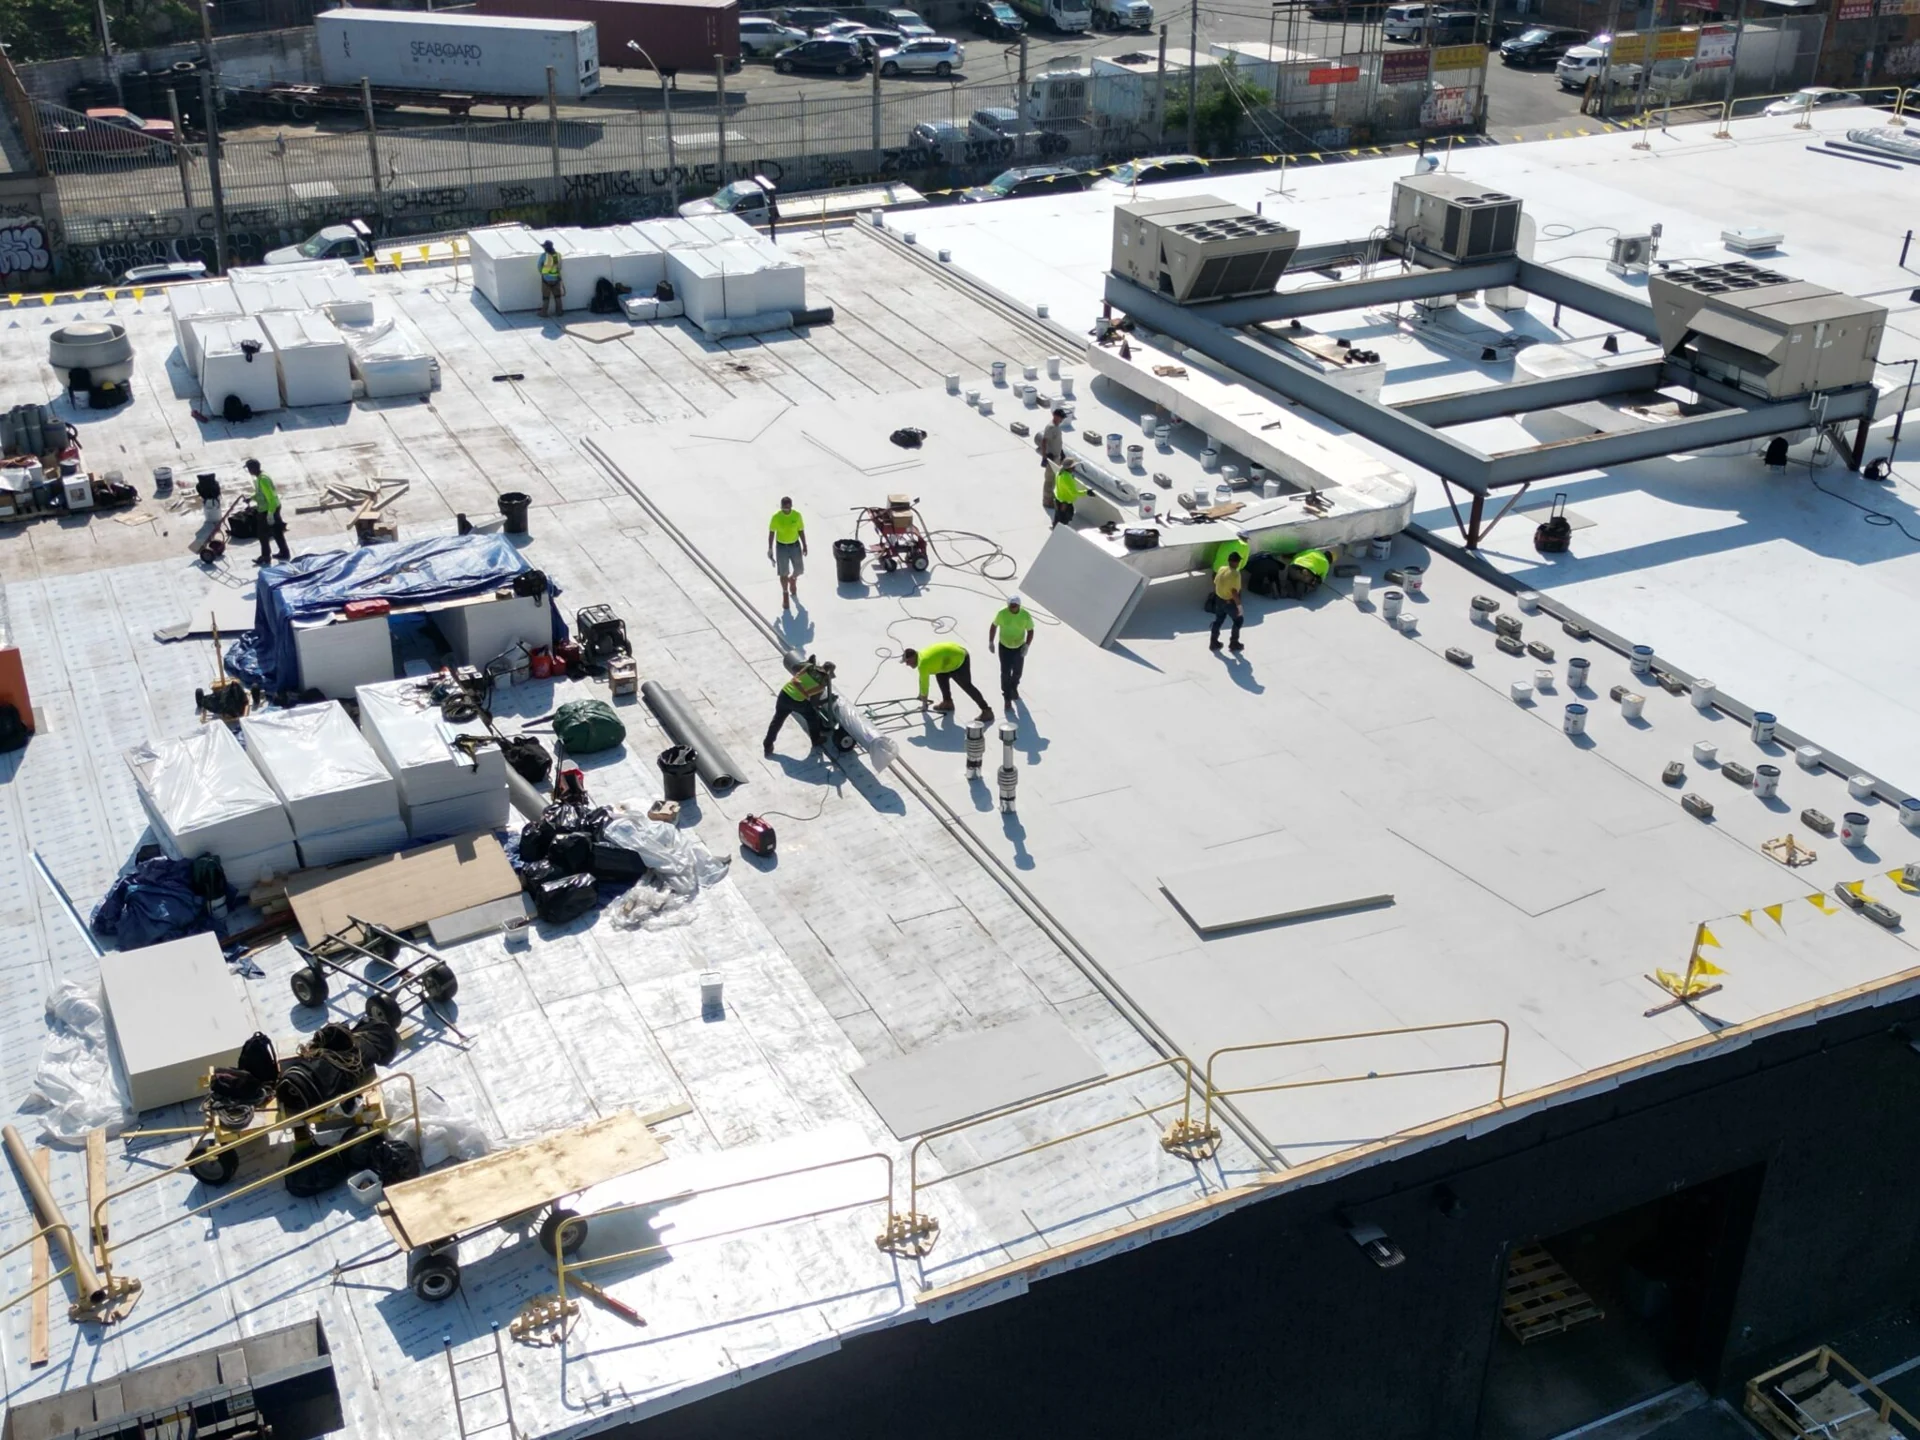
Funding built around the trade
Business funding for roofing companies.
Move through storm volume, supplier bills, crews, and insurance-payment delays with a plan that fits the season.
Where capital can help
Be ready when the work arrives at once.
Roofing cash flow can turn quickly after a storm or large commercial award. Materials and labor ramp now, while insurance proceeds, supplements, retainage, or customer payments can take longer to arrive.
Lock in material orders
Secure shingles, membrane, metal, insulation, and accessories before supplier pricing or availability changes.
Ramp production crews
Add labor, subcontractors, dump trailers, safety equipment, and field management when the sold backlog spikes.
Bridge insurance timing
Carry approved work while supplements, mortgage endorsements, or insurer payments move through the process.
Scale a proven channel
Support a measured canvassing, referral, or digital campaign only when close rate, install capacity, and unit economics are known.
 Seasonal speed still needs disciplined cash-flow math.
Who this helps—and when funding is not the fix.
The strongest request connects the cost, the job or operating need, and the source of repayment. Capital should bridge a timing gap or add productive capacity, not cover a broken margin.
Often a strong fit
- Established roofers with consistent deposits and visible sold backlog
- Seasonal or storm-driven volume with measurable material and labor needs
- Commercial or insurance work with documented contracts, claims, and payment stages
Usually not the first move
- Borrowing against unsigned estimates or an unproven storm market
- Lead spend without the sales team, production capacity, or close-rate data to support it
- Using high-frequency debt while insurance receivables remain uncertain or disputed
Ask suppliers about terms and job-specific credit, tighten customer deposit and progress-payment practices, or use equipment financing for trucks and production assets. If the season can wait, lower-cost term capital may be worth the longer process.
What strengthens the file
Bring the numbers behind the work.
A clean roofing file shows sold jobs, expected install dates, material commitments, production capacity, and how insurance or customer payments reach the account. Keep supplements and disputed claims separate from approved receivables.
Best practices before you take the money.
Finance the real gap, match repayment to how the business gets paid, and preserve enough room for payroll, suppliers, and the ordinary surprises of field work.
Plan beyond peak season
Stress-test payments against an ordinary month, not the first weeks after a storm.
Tie spend to installed revenue
Do not let marketing and material orders outrun crew and production capacity.
Protect supplement risk
Treat unapproved insurance supplements as upside, not guaranteed repayment.
Watch the fleet math
Finance trucks and equipment against real utilization and maintenance savings.
Availability, approval, amount, pricing, collateral, terms, documentation, and timing depend on the provider and the complete file. Axon Business Group is a financing brokerage, not a direct lender.
Bring the job, the numbers, and the timing.
Start with a quick fit check. If the file makes sense, the details are easier to explain over a short call.