Property project financing
Fix & flip financing with a disciplined exit.
Review capital for a qualified acquisition and renovation plan without treating short-term project money like permanent financing.
Specific situations
Match the financing to the project plan.
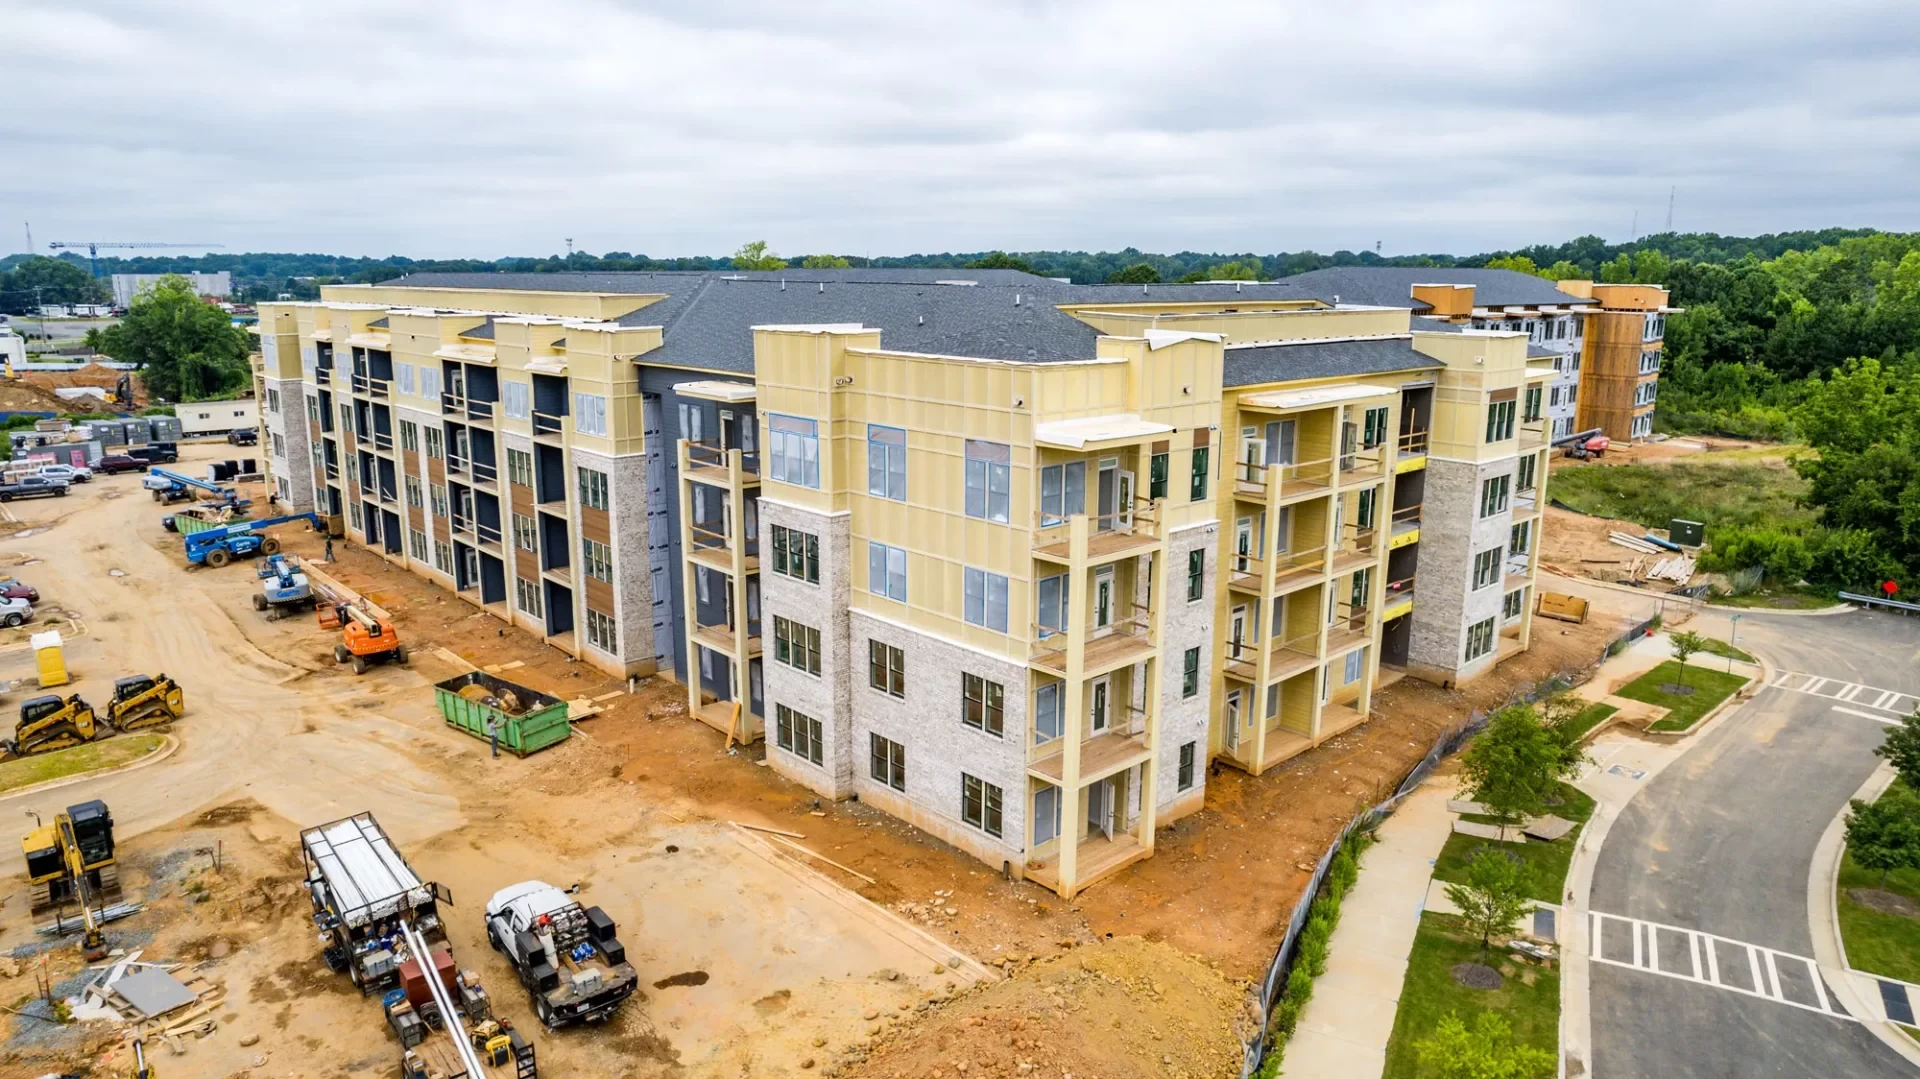
A stronger fix-and-flip request connects the purchase, scope of work, rehab budget, schedule, contingency and exit strategy before the deal reaches underwriting.
Close on a time-sensitive acquisition
Move on a property when the basis, scope and exit can be documented before the opportunity moves.
Complete a defined renovation
Connect every draw request to a real scope, contractor plan, timeline and contingency.
Finish a stalled project
Bring a partially completed property to sale or refinance when the remaining work and capital stack are clear.
Bridge to sale or permanent debt
Use short-term project capital only when the post-renovation exit is credible and the timeline has room for delays.
 The strongest project starts with a disciplined exit.
Who this helps—and when it may not.
The strongest financing choice is not always the fastest or the largest. It is the one whose structure fits the use, timeline, and cash cycle.
Often a strong fit
- A defined property, purchase basis, scope and budget
- Experienced operators or a credible project team
- A realistic sale, refinance or hold strategy with reserves
Usually not the first choice
- A ground-up project without the right construction financing
- A deal that only works at the most optimistic resale value
- An owner without enough liquidity for overruns, carry or required equity
Ground-up construction may need specialized construction debt or equity. A long-term rental hold may fit permanent real-estate financing after stabilization. General business expenses may belong in a line of credit or term structure instead.
What underwriting sees
A strong file tells a clean story.
Providers may review the property, purchase price, rehab scope, estimated value, borrower or project-team experience, liquidity, reserves, timeline, and proposed sale or refinance.
Best practices before you sign.
Bring the use, timing, and cash-flow math into the same decision. These are the questions that keep a useful product from becoming the next pressure point.
Build from the exit backward
Test the sale or refinance against conservative value, timing and cost assumptions.
Budget the whole hold
Include taxes, insurance, utilities, interest, permits, selling costs and delays.
Control the scope
Use written bids, draw schedules and a contingency sized to the property—not a round-number guess.
Protect closing certainty
Prepare entity documents, liquidity evidence, experience and property files before the deadline.
Availability, approval, amount, pricing, collateral, terms, documentation, and timing depend on the provider and the complete file. Axon Business Group is a financing brokerage, not a direct lender.
Get the structure, not just the headline number.
Review payment frequency, term, total repayment, fees, payoff language, and cash-flow impact before moving forward.