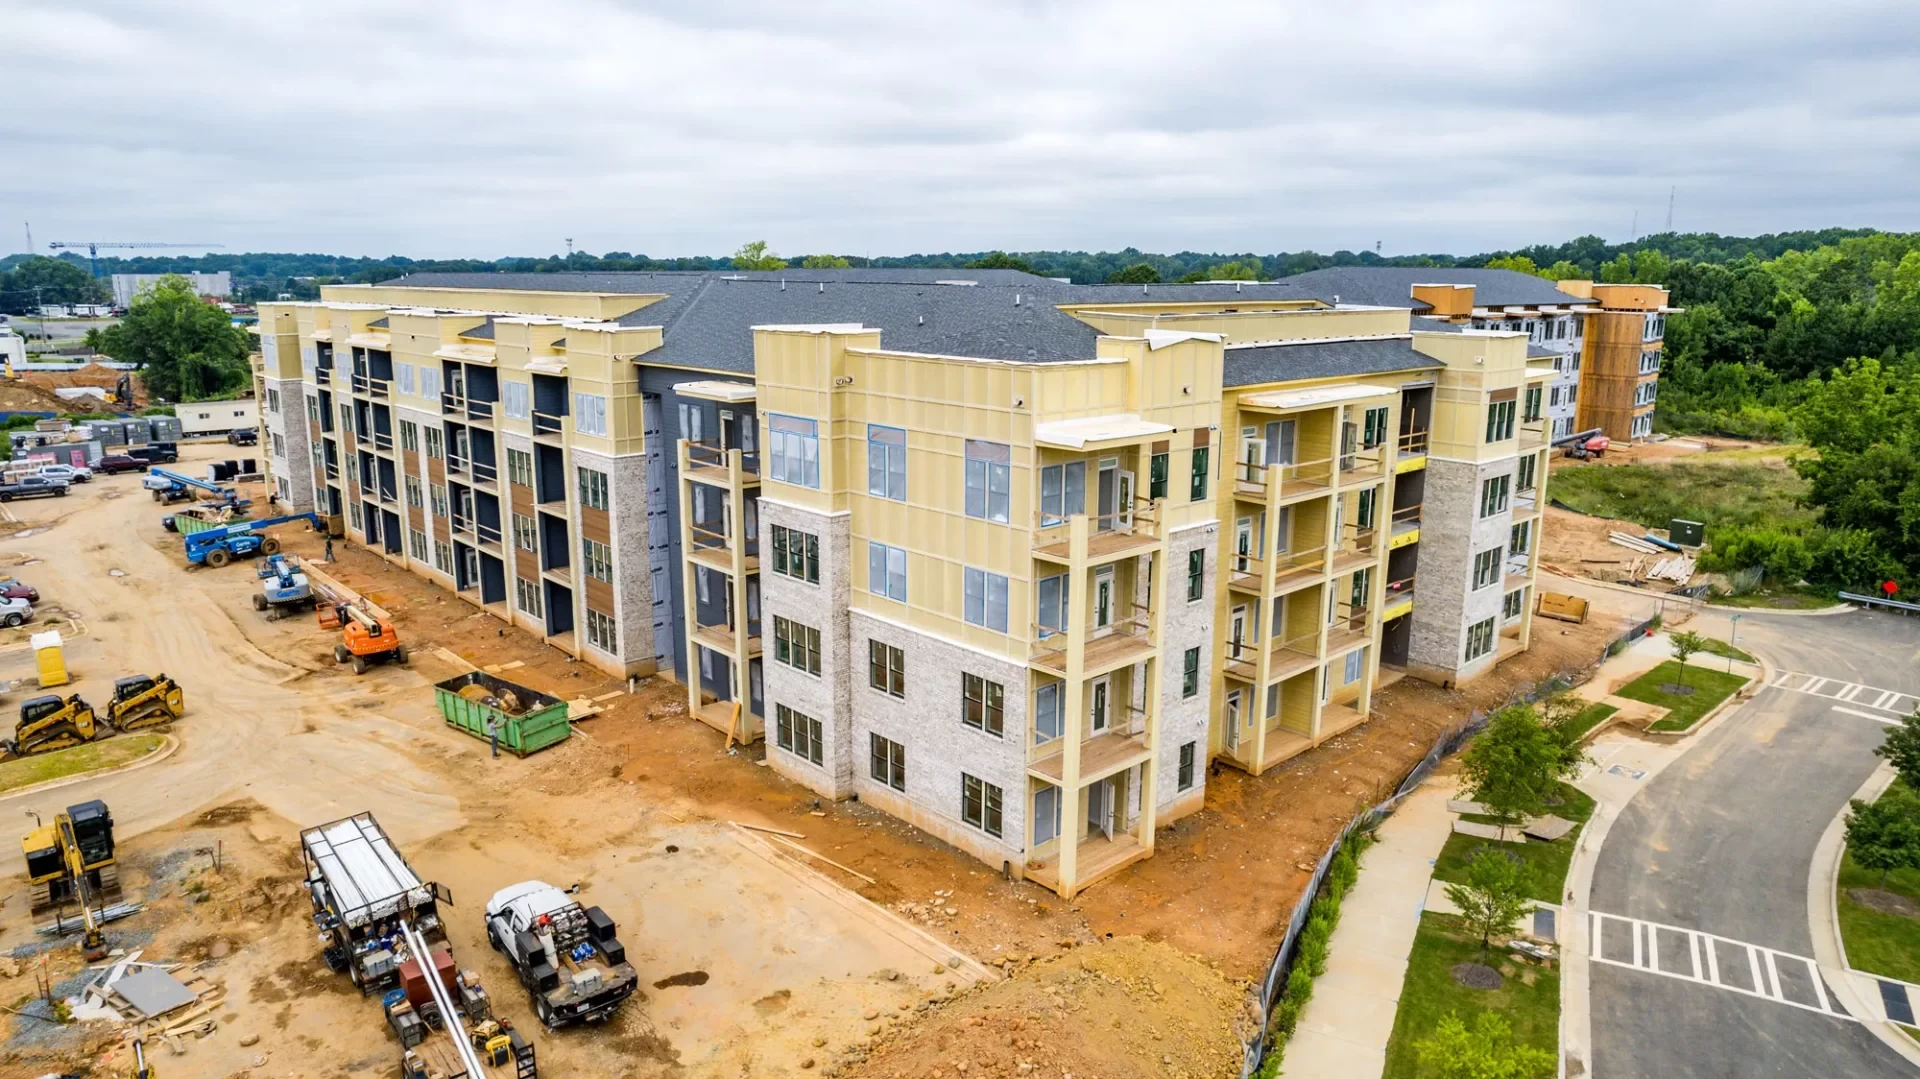
Rental acquisition & refinance
Long-term rental loans for durable hold strategies.
Finance or refinance a stabilized rental property around documented income, expenses, debt service, value, reserves, and the operator’s long-term plan.
Specific situations
Build the payment around the hold.
Long-term rental financing is designed for ownership beyond a quick resale. Depending on the product, underwriting may focus on property cash flow, borrower strength, lease quality, occupancy, reserves, and debt-service coverage.
Acquire a stabilized rental
Finance a property with documented rents, occupancy, expenses, condition, and a realistic long-term operating plan.
Refinance short-term project debt
Move a completed or stabilized property out of bridge or rehab financing into a structure meant for the hold.
Pull equity for the next investment
Access eligible equity without weakening debt-service coverage or stripping the property of needed reserves.
Improve an operating portfolio
Use a deliberate refinance to simplify maturities, improve cash flow, or fund measured property improvements.
 Permanent financing should support a permanent hold.
Who this helps—and when it may not.
The strongest financing choice is not always the fastest or the largest. It is the one whose structure fits the use, timeline, and cash cycle.
Often a strong fit
- Stabilized or near-stabilized properties with supportable rent
- Experienced owners with adequate liquidity and reserves
- A hold plan that works after vacancy, repairs, taxes, insurance, and management
Usually not the first choice
- Heavy construction or lease-up risk before stabilization
- A property whose income cannot support the proposed debt
- A short resale plan better matched to bridge or fix-and-flip financing
Use fix-and-flip or bridge financing during a short renovation or transition, then refinance after stabilization. Ground-up multifamily belongs in a development or construction structure.
What underwriting sees
A strong file tells a clean story.
A clean rental file separates real recurring income from optimistic projections and shows enough coverage for debt service, repairs, taxes, insurance, vacancy, and reserves.
Best practices before you sign.
Bring the use, timing, and cash-flow math into the same decision. These are the questions that keep a useful product from becoming the next pressure point.
Use conservative income
Underwrite vacancy, concessions, repairs, management, taxes, and insurance—not gross rent alone.
Match term to strategy
Avoid short maturity risk when the intention is a multi-year hold.
Protect reserves
Keep enough liquidity for turnover, capital expenditures, and unexpected repairs after closing.
Review recourse and prepayment
Understand guarantees, yield maintenance, defeasance, step-downs, and refinance flexibility.
Availability, approval, amount, pricing, collateral, terms, documentation, and timing depend on the provider and the complete file. Axon Business Group is a financing brokerage, not a direct lender.
Get the structure, not just the headline number.
Review payment frequency, term, total repayment, fees, payoff language, and cash-flow impact before moving forward.